Small Business Health Insurance
Compare health insurance for small and medium-sized businesses, with independent advice on cover, costs, underwriting and leading UK insurers.
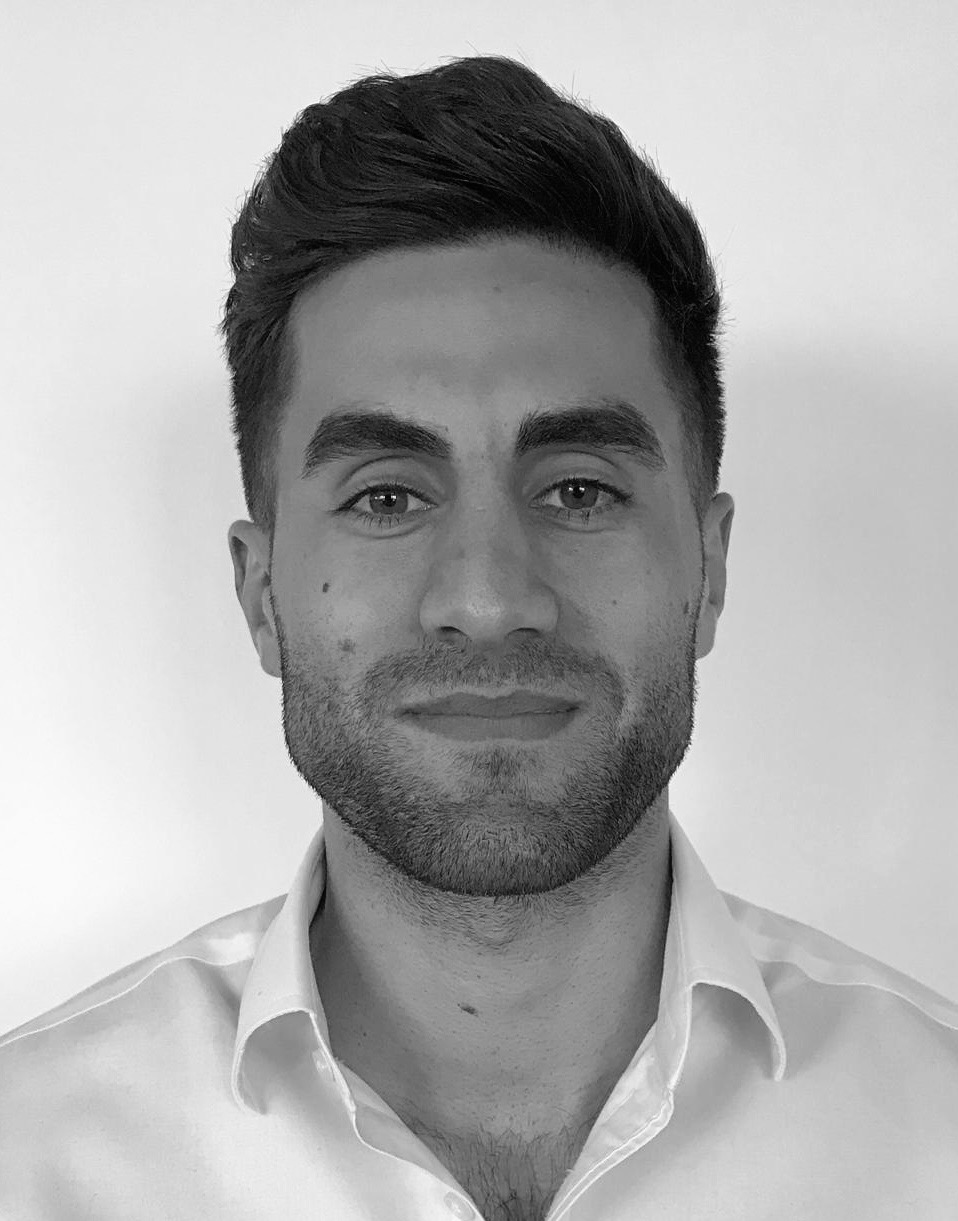
Louis has over 12 years' experience advising small businesses and SMEs on business health insurance.
What is small business health insurance?
Small business health insurance is private medical insurance arranged by a company for its eligible directors and employees. It works in a similar way to business health insurance more broadly, just scaled for smaller teams.
Depending on the insurer and scheme selected, cover can give eligible members access to private specialist consultations, diagnostic tests and scans, hospital treatment, surgery and cancer care, alongside what is available through the NHS.
Policies can typically be tailored around the level of outpatient cover, the hospitals and consultants members can access, the excess chosen, mental health benefits, and added services such as digital and remote healthcare.
A large workforce is not always required to arrange business health insurance. However, eligibility rules and any minimum group sizes differ between insurers and underwriting options, so it is worth having your specific circumstances reviewed before choosing a policy.
Small business health insurance is also commonly referred to as SME health insurance, reflecting the range of small and medium-sized businesses it can suit.
Who is small business health insurance for?
Small business private health insurance can suit a wide range of small and medium-sized businesses, from owner-managed companies to growing teams of employees.
Small Limited Companies
Owner-managed businesses looking to arrange private healthcare for the people running the company.
Companies With a Handful of Employees
Businesses wanting to provide a valued employee health insurance benefit to a small, close-knit team.
Growing SMEs
Companies planning ahead as headcount increases and benefit requirements evolve.
Professional & Consultancy Firms
Firms wanting to support senior staff and consultants with private medical insurance for employees.
Trades & Contracting Businesses
Physically demanding businesses may also find our guide to health insurance for tradesmen and contractors useful.
First-Time & Existing Schemes
Companies arranging company health insurance for the first time, or reviewing a scheme that is already in place.
What is available to your business depends on your company structure, who is eligible to be included, and each insurer's own eligibility rules. If you are self-employed rather than trading through a limited company, our guide to private health insurance for self-employed people and sole traders may be more relevant.
What does small business health insurance cover?
Benefits, limits and exclusions vary between insurers and policies. The following are commonly available, subject to the terms of the scheme selected.
Specialist Consultations
Eligible appointments with private consultants for diagnosis and ongoing advice.
Diagnostic Tests and Scans
Eligible blood tests, X-rays, ultrasound, MRI, CT and PET scans, depending on the policy.
Inpatient & Day-Patient Treatment
Eligible hospital admission, surgery and associated treatment as an inpatient or day patient.
Cancer Cover
Eligible cancer treatment, though the exact scope of cover varies between insurers.
Mental Health
Many policies now include some level of eligible mental health support, though benefits vary.
Therapies
Eligible physiotherapy and other recognised therapies, depending on the insurer.
Digital & Remote Healthcare
Remote GP services and digital health tools included with many modern policies.
How much does small business health insurance cost?
There is no single price for small business health insurance. Premiums can be affected by a number of factors, including:
- The number of members and their ages
- Your business location
- The level of outpatient cover chosen
- Hospital and consultant access
- The excess selected
- The underwriting basis used
- Any additional benefits included
- Previous claims and scheme history, where relevant
- The insurer selected
Because of this, we always recommend comparing suitable options for your specific circumstances rather than relying on a generic figure.
Illustrative monthly pricing snapshot
The figures above are total monthly example premiums for the five-employee group illustrated (ages 40, 45, 45, 50, 50, median age 45), based on rates supplied to Elective Health on 17 September 2026. They are illustrative examples only and are not quotations or guarantees. Actual premiums depend on member details, postcode, cover selected, underwriting basis, insurer and quote date.
Is business health insurance only for large companies?
No. Small companies can arrange cover for just a handful of directors or employees.
The options available to your business depend on how many people are eligible to be included and the rules of the scheme you choose. Some underwriting arrangements, such as Medical History Disregarded, require a minimum group size, while other arrangements may be available to smaller eligible businesses, subject to the insurer's rules.
It is also worth thinking about how your cover would work as the business grows. A scheme that suits two employees today may need reviewing once you employ five or ten.
Small business health insurance vs individual health insurance
Individual Health Insurance
An individual policy belongs to the individual, even where a limited company pays the premium on their behalf. This can suit a sole director or a very small company where only one or two people need cover.
Read our guide to Private Health Insurance for Company Directors and Limited Companies, including how a limited company can pay for an individual policy.
Business Health Insurance Scheme
A business scheme is established by the company for its eligible members, such as directors and employees. As the business grows and takes on more staff, this can offer a more structured route for extending cover to the wider team, subject to the insurer's eligibility rules.
See Can My Limited Company Pay for My Private Health Insurance? for a fuller explanation of how each route works.
Neither route is universally better. The right structure depends on your company, who needs to be covered, and your plans for the business.
Can small business health insurance cover pre-existing conditions?
This depends entirely on the underwriting method used and the insurer's terms. Cover for a pre-existing condition can never be guaranteed in advance. Our full guide to underwriting explained covers this topic in more depth.
Full Medical Underwriting
Members provide their medical history when they apply, and the insurer confirms any exclusions in writing before cover begins, always subject to insurer acceptance.
Moratorium Underwriting
A simpler application with fewer upfront questions. Pre-existing conditions are generally assessed at the point of a claim, and eligibility for cover on those conditions depends on the insurer's moratorium terms.
Continued Underwriting / Switching Terms
When switching insurer, some previous underwriting terms may be able to continue, subject to the new insurer's acceptance. See our guide to switching health insurance for more detail.
Medical History Disregarded (MHD)
An option for certain eligible business schemes, where eligible members may be covered without previous medical history being used in the usual way, subject to the insurer's terms and policy exclusions. Learn more about Medical History Disregarded underwriting.
What is Medical History Disregarded health insurance?
Medical History Disregarded, or MHD, is an underwriting option available for certain eligible business schemes. Under MHD, eligible members may receive cover without their previous medical history being used in the usual way to set individual exclusions, subject to the insurer's terms and the policy's own exclusions.
Availability and any group size requirements differ between insurers, so this option will not suit every small business. We can confirm whether it is likely to be available for your circumstances.
Can a small business switch health insurance provider?
Yes, a small business can switch health insurance provider. However, this should never be decided on price alone. Before switching, it is worth reviewing:
- Your existing underwriting basis
- Any members currently receiving treatment
- Ongoing or planned investigations
- Previous claims history
- Hospital and consultant access
- Outpatient benefits
- Excess levels
- Cancer cover
- Employee eligibility rules
- The new insurer's terms
- Your renewal premium
Changing provider without understanding how existing and pre-existing conditions will be treated under the new policy can cause real problems if a member later needs to claim. Our guide to switching health insurance explains the process in more detail.
Small business health insurance and tax
Company-paid private medical insurance can have tax implications, including the possibility of it being treated as a Benefit in Kind for the individual covered.
The insurance arrangement and your individual tax treatment are separate matters. Elective Health advises on the insurance arrangement itself. We do not provide tax or accountancy advice, so questions relating to Corporation Tax, Benefit in Kind, P11D reporting, payroll or your individual tax position should be directed to an accountant or qualified tax adviser.
Our guide to Is Private Health Insurance Tax Deductible for a Limited Company? and Can My Limited Company Pay for My Private Health Insurance? covers these subjects in more depth.
Why offer private health insurance to employees?
Private medical insurance for employees can support your team in a number of practical ways:
- Supporting the wellbeing of directors and employees
- Giving eligible members access to private diagnosis and treatment
- Providing a benefit that many employees value
- Supporting recruitment and staff retention
- Offering greater choice over where and when treatment takes place
- Helping members access care around work and personal commitments
We would not suggest that health insurance guarantees reduced staff absence or improved productivity. Every business and every member's circumstances are different, but many employers find it a genuinely valued part of their overall benefits package.
How to compare small business health insurance
Don't compare premium alone
The lowest monthly premium does not necessarily represent the best value. A cheaper policy may include a restricted hospital list, a lower outpatient limit or a higher excess.
Check outpatient cover
Some policies provide full outpatient cover, while others apply a monetary limit shared across consultations, tests and scans. A lower headline limit can be used up faster than expected if a member needs several tests.
Check hospital access
Compare whether members have access to a wide hospital network or a guided consultant option, where the insurer directs members towards a shortlist of specialists in exchange for a lower premium.
Check the excess
A higher excess can reduce the premium, but it is worth understanding how often the excess applies, for example once per person per year or per claim, before comparing on price.
Check underwriting
How medical history is assessed, both now and if you ever switch insurer, can significantly affect what a member can claim for.
Check cancer and mental health benefits
These benefits vary considerably between insurers, so it is worth checking the detail rather than assuming all policies are equivalent.
Think about future growth
Consider how your scheme would work if you take on more employees, and whether that could open up different underwriting options such as Medical History Disregarded.
Why use Elective Health for small business health insurance?
Arranging health insurance for a small business involves a number of practical decisions, from choosing between an individual or business structure through to understanding underwriting and comparing hospital access. As independent, FCA-regulated advisers, we take the time to understand your requirements, review any existing cover, and compare suitable options from leading UK insurers.
We will explain the differences between policies and underwriting methods in plain English, clarify what switching would mean for your existing cover, support you through the application, and review your scheme at renewal.
- 5.0 stars on Google from 46 independent reviews
- Over 12 years' experience advising businesses on health insurance
- UK-based support, direct from Kingsley and Louis
- No call centres
- Independent advice from a carefully selected panel of leading UK insurers
Small Business Health Insurance FAQs
Compare Small Business Health Insurance
Whether you're arranging private health insurance for your business for the first time or reviewing an existing scheme, Elective Health can help you understand the options and compare suitable cover. Speak to an adviser for an independent review of your small business health insurance options.